 Written by
 Edited by

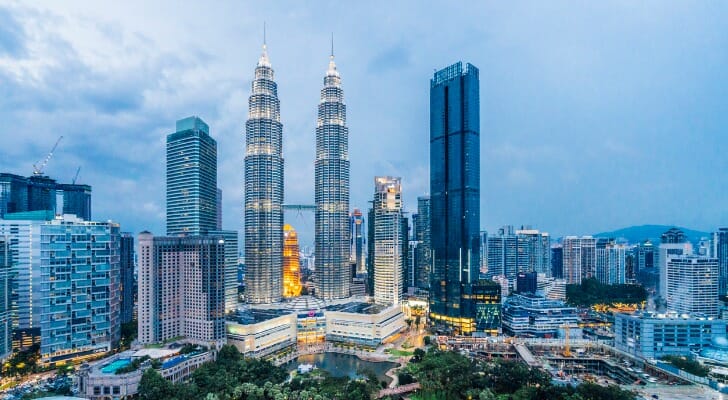
Malaysia can appeal to retirees who want access to large cities, beaches and tropical areas. As a major bonus, retirees can potentially spend less than they would to retire in many parts of the United States. Before relocating, however, you’ll need to consider living expenses, residency requirements, healthcare, housing and taxes.
A financial advisor can also help you get your plans in order for a retirement abroad.
Cost of Living in Malaysia
When planning for retirement, it’s important to evaluate your anticipated cost of living. This includes housing, utilities, travel and lifestyle-related expenses. Conducting a thorough cost analysis will help determine if relocating to Malaysia aligns with your financial goals and budget.
As of September 2026, Numbeo reports that the overall cost of living in Malaysia is approximately 51% lower than in the United States, excluding rent. Renting in Malaysia is, on average, 79.8% less expensive than in the United States.
Your specific expenses will vary based on your lifestyle and chosen location. For instance, in Kuala Lumpur, the capital of Malaysia, a one-bedroom apartment in the city center averages around $610 per month, while the same outside the city center costs about $371. Meanwhile, in Ipoh, a smaller city, a one-bedroom apartment in the city center averages approximately $371 per month, and about $247 outside the city center.
Many expatriates opt to reside on Penang Island, known for its rich culture and coastal beauty. According to International Living, retirees can live comfortably on $2,500 per month. This includes renting a three-bedroom condo with a balcony overlooking the ocean. For those who prefer more modest accommodations, $2,000 per month is sufficient to maintain a comfortable lifestyle.
Visa Laws in Malaysia
U.S. citizens traveling to Malaysia for visits of up to 90 days generally do not need to obtain a tourist visa in advance. A short-term visit, however, is different from establishing long-term residency.
Retirees who want to remain in Malaysia for an extended period need an appropriate immigration status. One option is the Malaysia My Second Home program, commonly known as MM2H. The program has undergone substantial changes in recent years, so older descriptions of its financial and residency requirements may no longer apply.
Immigration requirements can also vary depending on the type of pass involved. Retirees should verify the current rules with Malaysian authorities before relocating. Avoid relying on the requirements that applied when you previously visited the country, as those may no longer be current.
Healthcare in Malaysia
Malaysia has both public and private healthcare systems. Foreign retirees commonly use private hospitals and clinics, particularly in larger cities where facilities that serve international patients are more widely available.
English is commonly used in private healthcare settings. This can make it easier for American retirees to communicate with doctors and other medical professionals. Malaysia has also developed a medical tourism industry that serves patients traveling from other countries for treatment.
Costs depend on the hospital, treatment and level of coverage. Retirees should therefore avoid assuming that a particular consultation, hospital stay or procedure will cost the same across Malaysia.
Private health insurance can help cover medical expenses. However, premiums and eligibility can vary based on age, medical history and coverage. Before relocating, it can be useful to compare policies and determine how prescription drugs, specialist treatment and hospital care would be covered.
Medicare generally does not cover healthcare received outside the United States except in limited circumstances. That makes planning for medical expenses particularly important for Americans retiring abroad.
Housing Costs in Malaysia
When planning your move, housing is one of the most significant factors to consider. Many retirees are drawn to Penang, an island state in northwest Malaysia, for its relaxed lifestyle and scenic beaches. However, if beaches aren’t your preference, Kuala Lumpur or the southern state of Johor also offer attractive living options.
Housing costs vary based on location and lifestyle preferences. In Kuala Lumpur, the average cost of a home in city center is around $381 per square foot. Meanwhile, in Penang, it’s about $206 per square foot. For comparison, homes in New York City average $1,743 per square foot. This makes Malaysian housing remarkably affordable by international standards.
Home Buying in Malaysia
Foreigners can buy a home in Malaysia, but the rules are more restrictive than they are for Malaysian citizens. Property purchases by foreigners can be subject to state approval, minimum purchase prices and restrictions on certain categories of real estate.
The applicable minimum price can vary by state. As such, there is no single purchase threshold that applies to every foreign buyer throughout Malaysia. Buyers should check the rules for the state where the property is located before making an offer.
Once you’ve identified an area where you’d like to live, you can work with a local real estate agent to compare properties and determine how much you can afford. A Malaysian lawyer can review the title, purchase agreement and applicable restrictions before the transaction is completed.
Foreign buyers may also need to account for a down payment, stamp duty, legal fees and other transaction costs. Financing may be available from Malaysian banks. However, loan terms and required down payments can differ for foreign borrowers.
MM2H participants have an additional consideration. The current federal program requires participants to purchase residential property, with the minimum value determined by their MM2H category. Those requirements do not necessarily replace other state-level rules governing foreign property ownership.
Because buying property overseas can involve unfamiliar legal and financing rules, conducting research and obtaining local legal advice before signing a purchase agreement can reduce the risk of unexpected restrictions or costs.
Malaysia My Second Home Program
The Malaysia My Second Home program provides a long-term residency option for qualifying foreigners. The federal program currently includes Silver, Gold and Platinum categories, along with a separate Special Economic Zone and Special Financial Zone category. Applicants for Silver, Gold and Platinum must generally be at least 25 years old.
The financial requirements vary considerably by category. Silver requires a fixed deposit of $150,000 in a qualifying Malaysian financial institution. Gold requires $500,000, and Platinum requires $1 million. The corresponding passes run for five, 15 and 20 years and are renewable.
The program also requires participants to purchase residential property after receiving approval. The minimum purchase is RM600,000 for Silver, RM1 million for Gold and RM2 million for Platinum. Participants generally cannot sell the required residence during the first 10 years. However, they can replace it with a more expensive qualifying property.
Participants under age 50 are generally subject to a requirement to spend at least 90 cumulative days in Malaysia each year. Work rights also depend on the MM2H category. Platinum participants may pursue employment and business or investment activities. However, those activities are not permitted under the Silver, Gold and Special Economic Zone categories without obtaining another appropriate pass.
Applications must go through an MM2H business licensed by Malaysia’s Ministry of Tourism, Arts and Culture. Because the program has changed repeatedly, retirees considering MM2H should check the current requirements before committing money to a fixed deposit or property purchase.
Taxes in Malaysia
Malaysia generally taxes income based on rules involving the source of the income, the taxpayer’s residency status and, in some cases, whether foreign-sourced income is received in Malaysia. Retirees therefore should not assume that every payment originating outside Malaysia is automatically exempt from Malaysian tax.
Tax treatment can also differ depending on whether the income comes from employment, investments, pensions or another source. Rules governing foreign-sourced income have changed in recent years. Because of this, it’s particularly important to check the treatment that applies during the tax year in question.
Americans who retire in Malaysia generally continue to have U.S. federal tax filing obligations. U.S. citizens are generally taxed on worldwide income even while living in another country. You may therefore still need to file taxes with the IRS after relocating.
Depending on the type of income involved and your circumstances, U.S. tax rules provide mechanisms that can sometimes reduce taxation associated with living and earning money overseas. Different provisions apply to earned income, housing expenses and foreign taxes already paid, so retirement income should not automatically be treated the same as wages earned abroad.
Foreign financial accounts can create additional reporting requirements. A U.S. person generally must file an FBAR if the combined value of covered foreign financial accounts exceeds $10,000 at any point during the calendar year. Certain taxpayers may also have to file Form 8938 for specified foreign financial assets.
Retirees with income or assets in both countries may benefit from working with a tax professional familiar with U.S. international tax rules and Malaysian taxation.
Bottom Line
Malaysia can offer retirees lower living costs than many parts of the United States, along with access to major cities, coastal communities and private healthcare. Americans considering a move should compare expenses in their preferred location and account for healthcare, housing and international tax obligations. Long-term residency also requires more planning than a short visit. The current MM2H program imposes fixed-deposit and property-purchase requirements that vary by category, while foreign home purchases can be subject to additional state rules. Reviewing these requirements before relocating can provide a clearer estimate of how much retiring in Malaysia will cost.
Tips for Retiring Overseas
- Consider talking to a financial advisor about making a plan for retiring overseas. Finding a qualified financial advisor doesn’t have to be hard. SmartAsset’s free tool matches you with financial advisors who serve your area. You can interview your advisor matches at no cost to decide which one is right for you. If you’re ready to find an advisor who can help you achieve your financial goals, get started now.
- An essential part of saving for retirement is making sure the money you save remains untouched. Dipping into your savings may seem tempting if you’re low on cash, but you’ll pay for it down the line. Consider creating an emergency fund instead.
Photo credit: ©iStock.com/FilippoBacci, ©iStock.com/stockstudioX, ©iStock.com/Sam Song